For pre-retirees and retirees 59+ with $1M+ in IRAs and 401(k)s — Find your optimal Roth conversion strategy
AI-Driven Insights

Stop RMDs from devastating your nest egg, spouse's security, and heirs' inheritance.
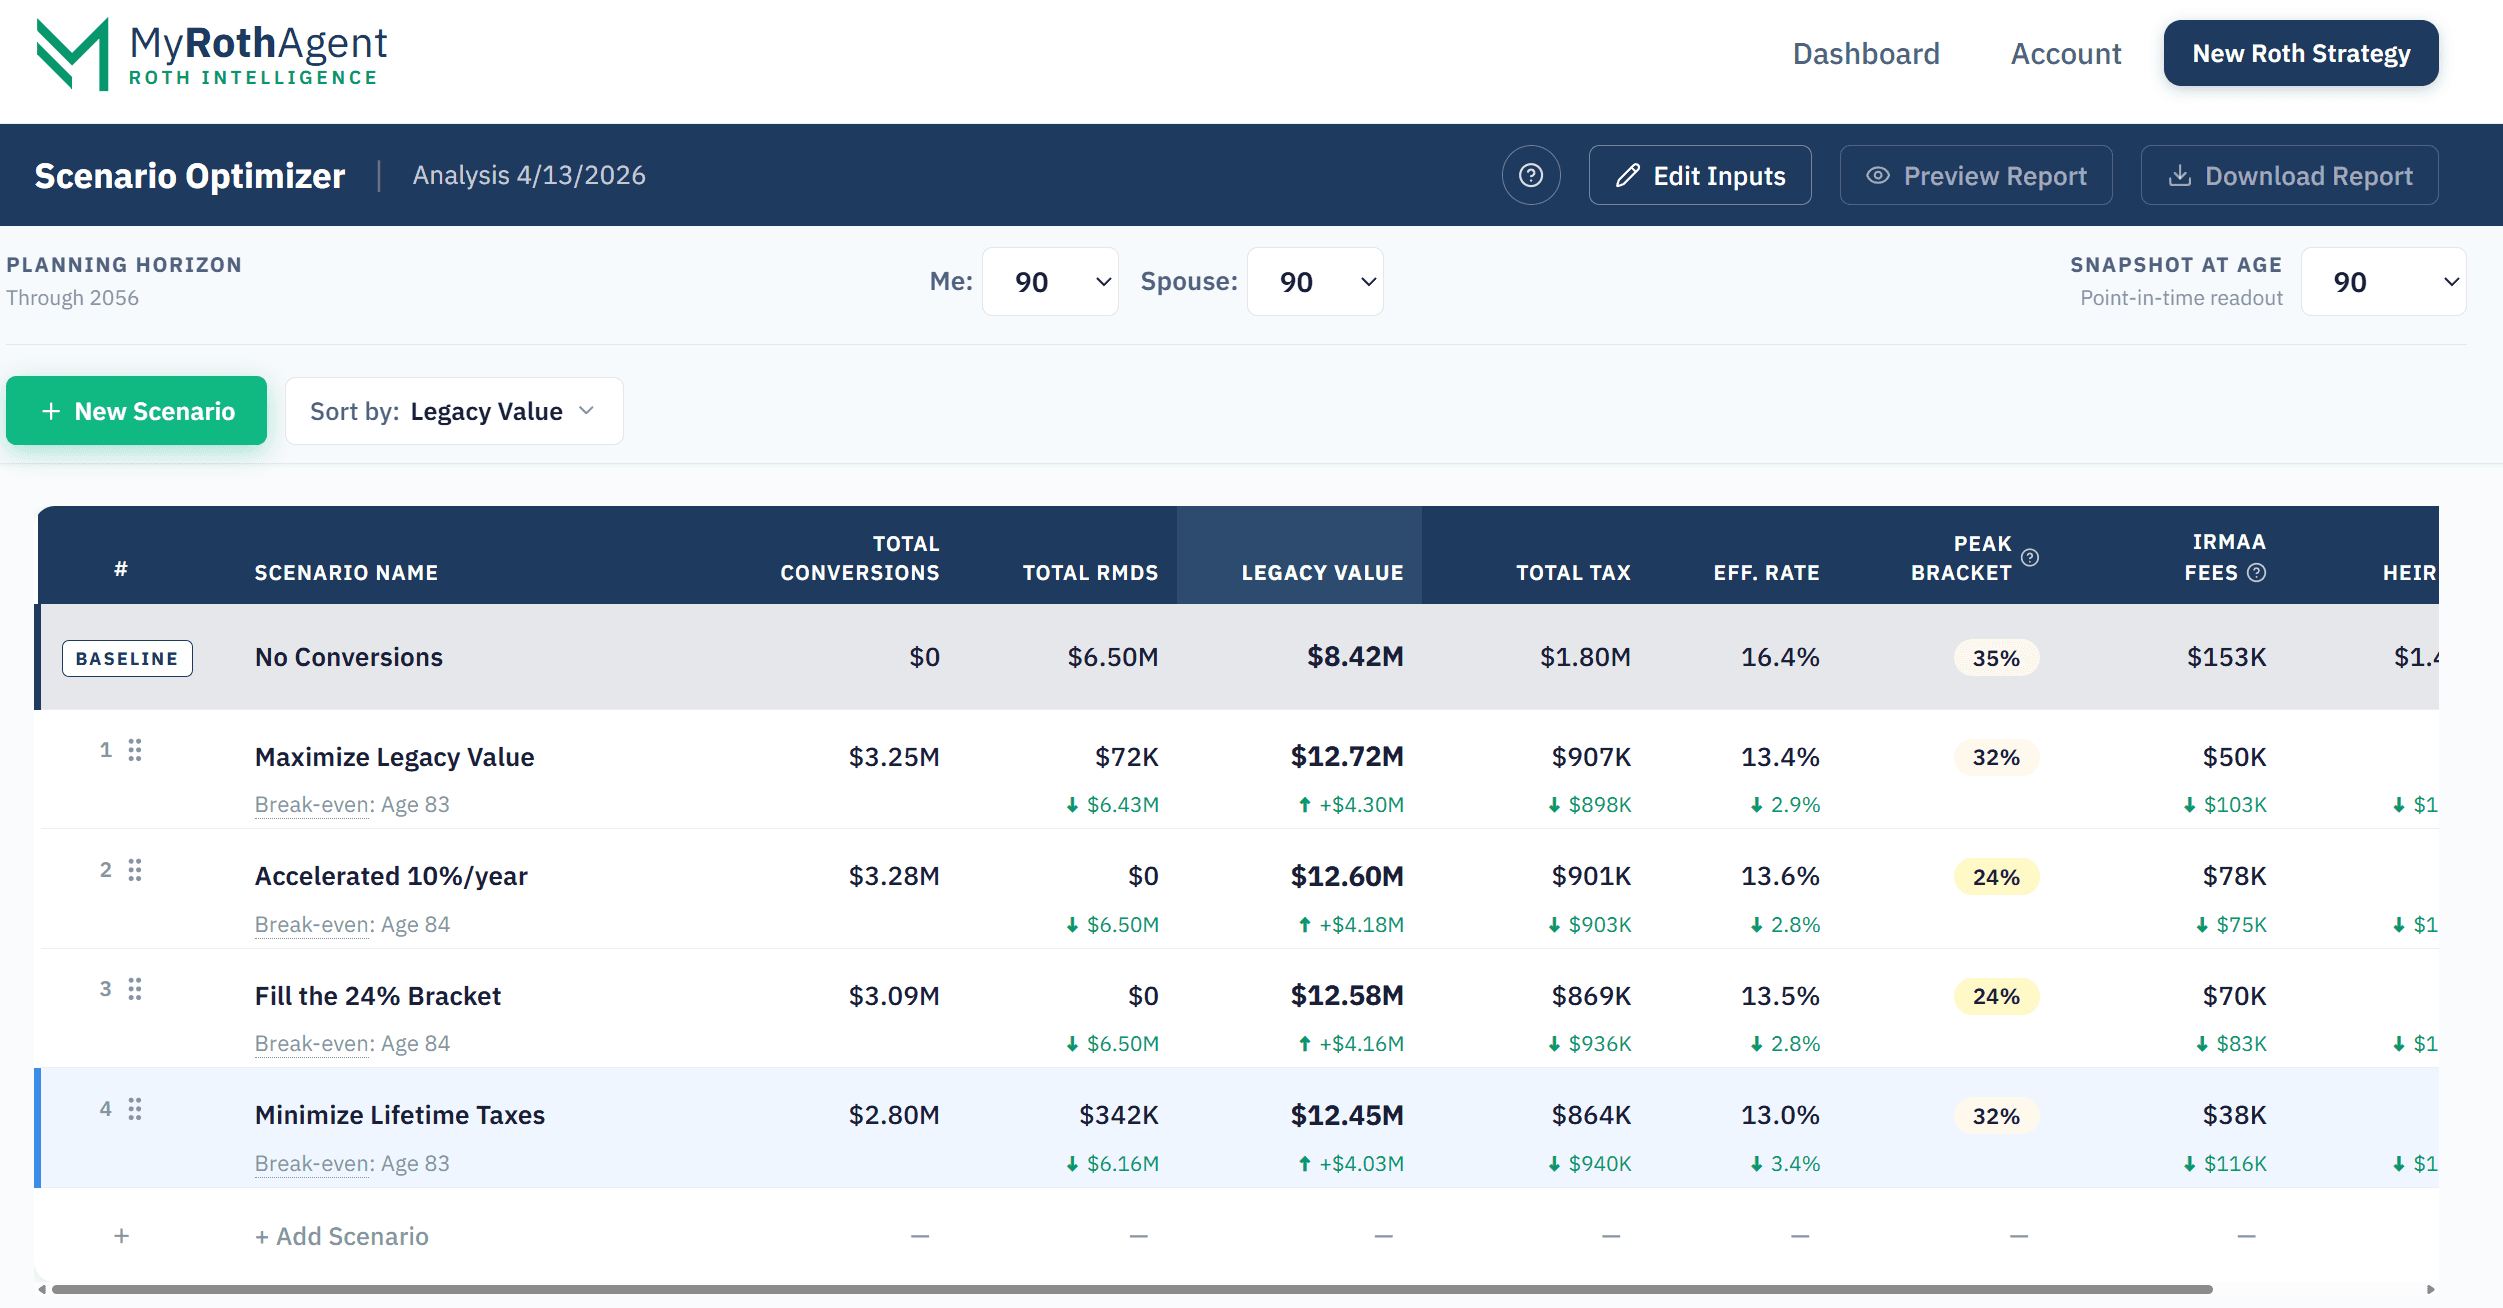
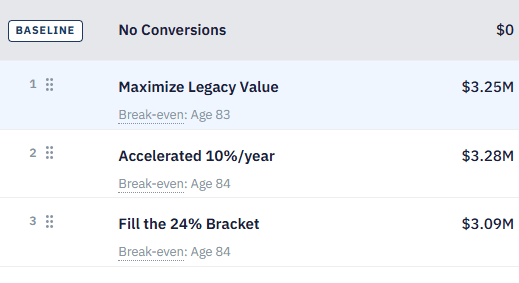
MyRothAgent Scenario Optimizer comparison table — 5 Roth conversion strategies vs baseline of doing nothing. Minimize Lifetime Taxes highlighted with $12.45M legacy value, $864K lifetime tax, $0 heir tax.
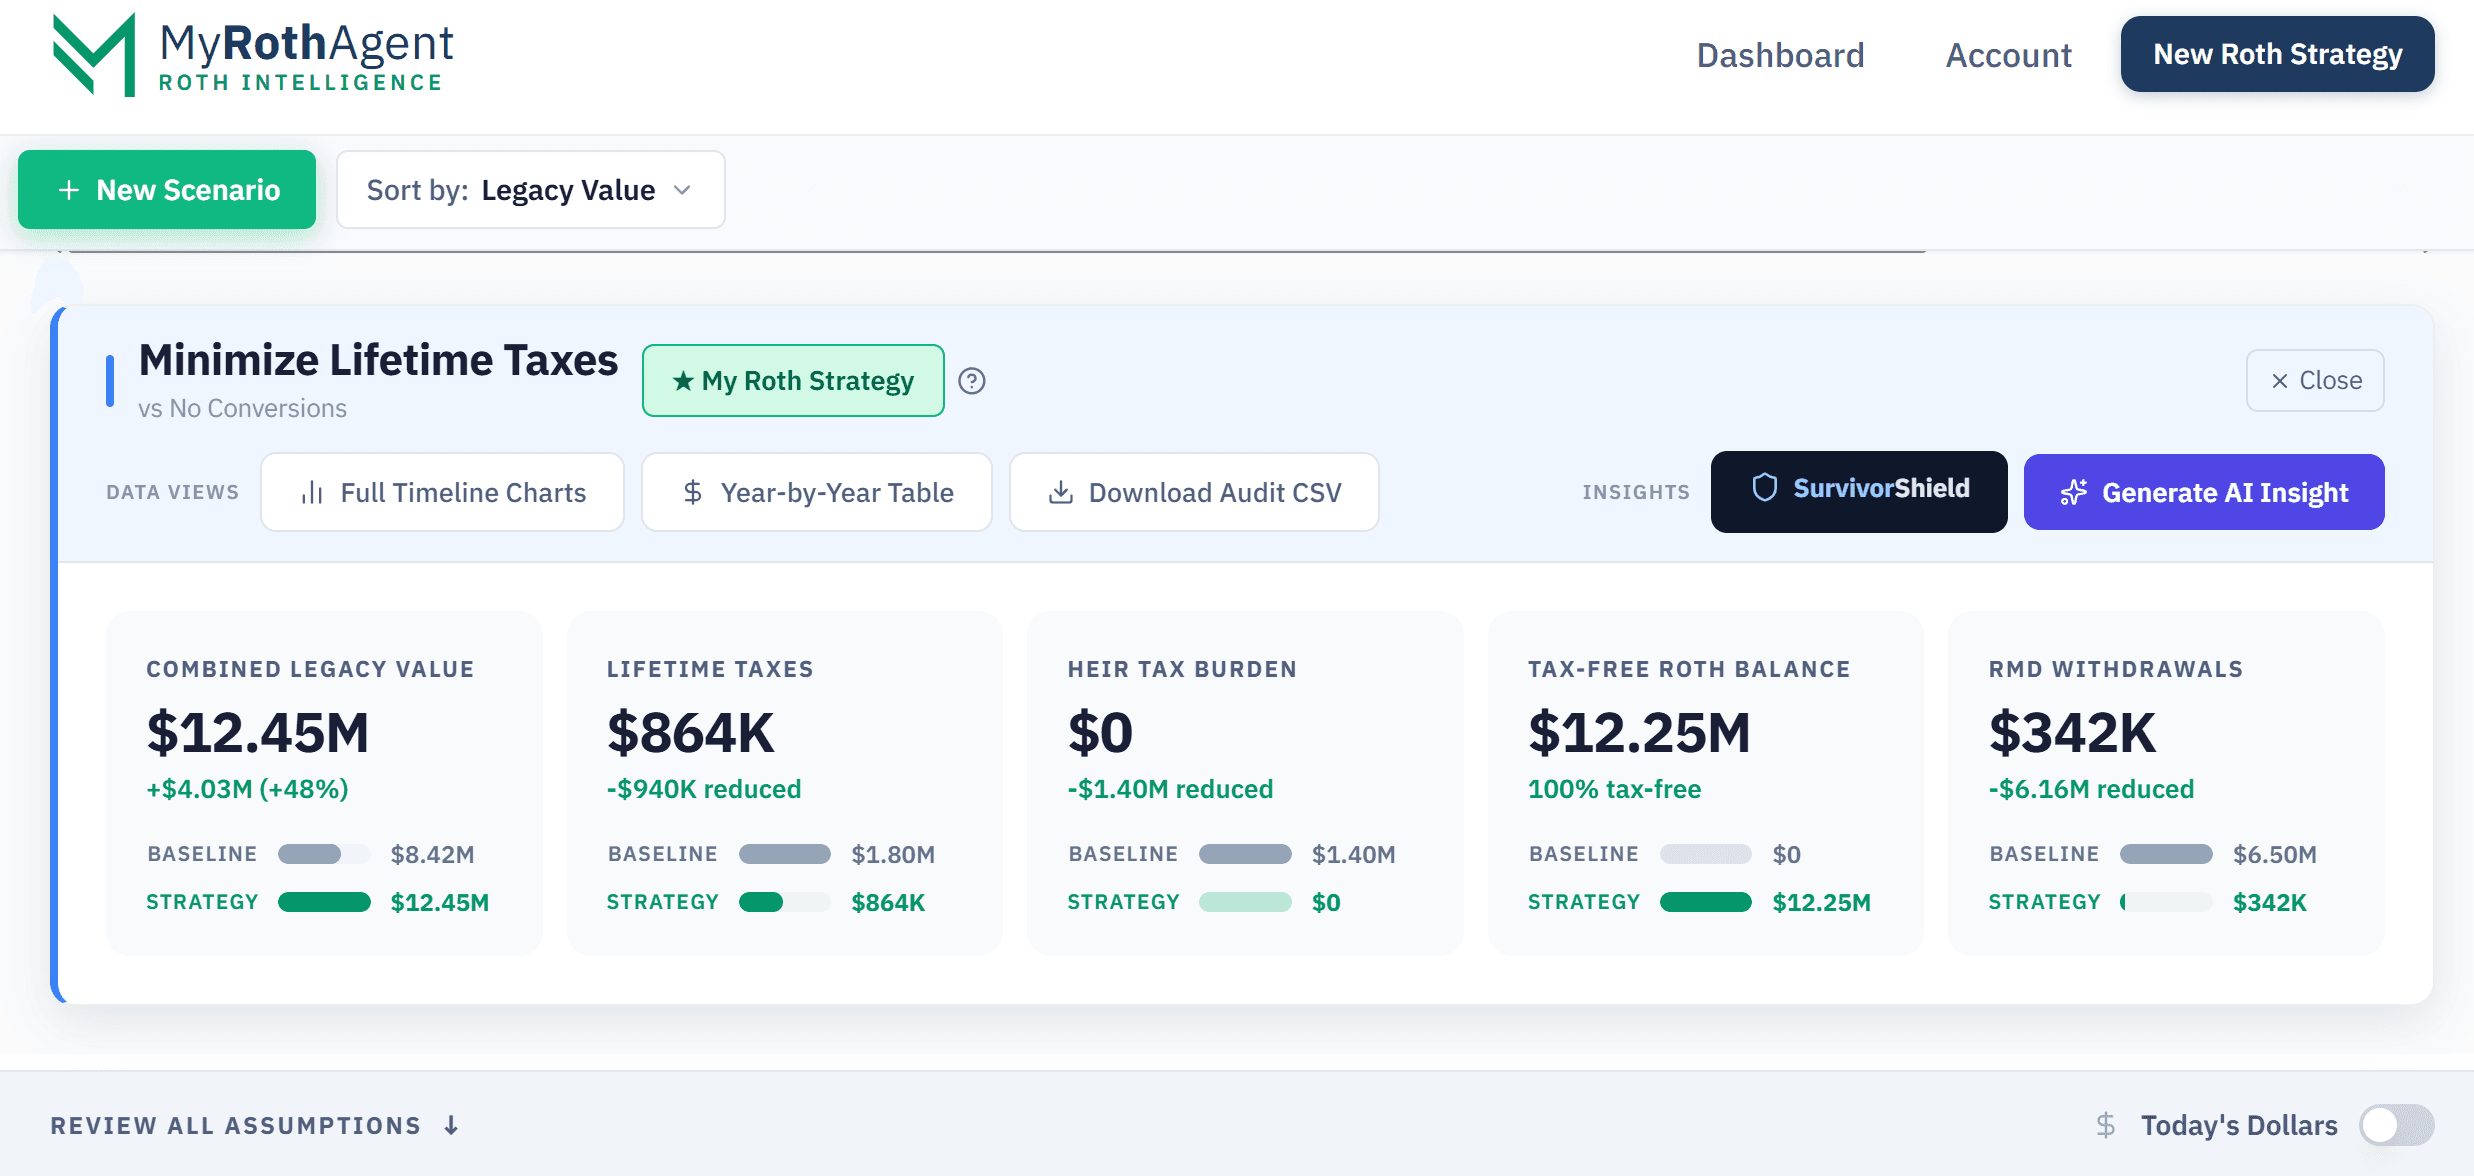
Minimize Lifetime Taxes strategy detail panel — $12.45M combined legacy value (+$4.03M / +48%), $864K lifetime taxes (-$940K reduced), $0 heir tax burden, $12.25M tax-free Roth balance, $342K RMD withdrawals.
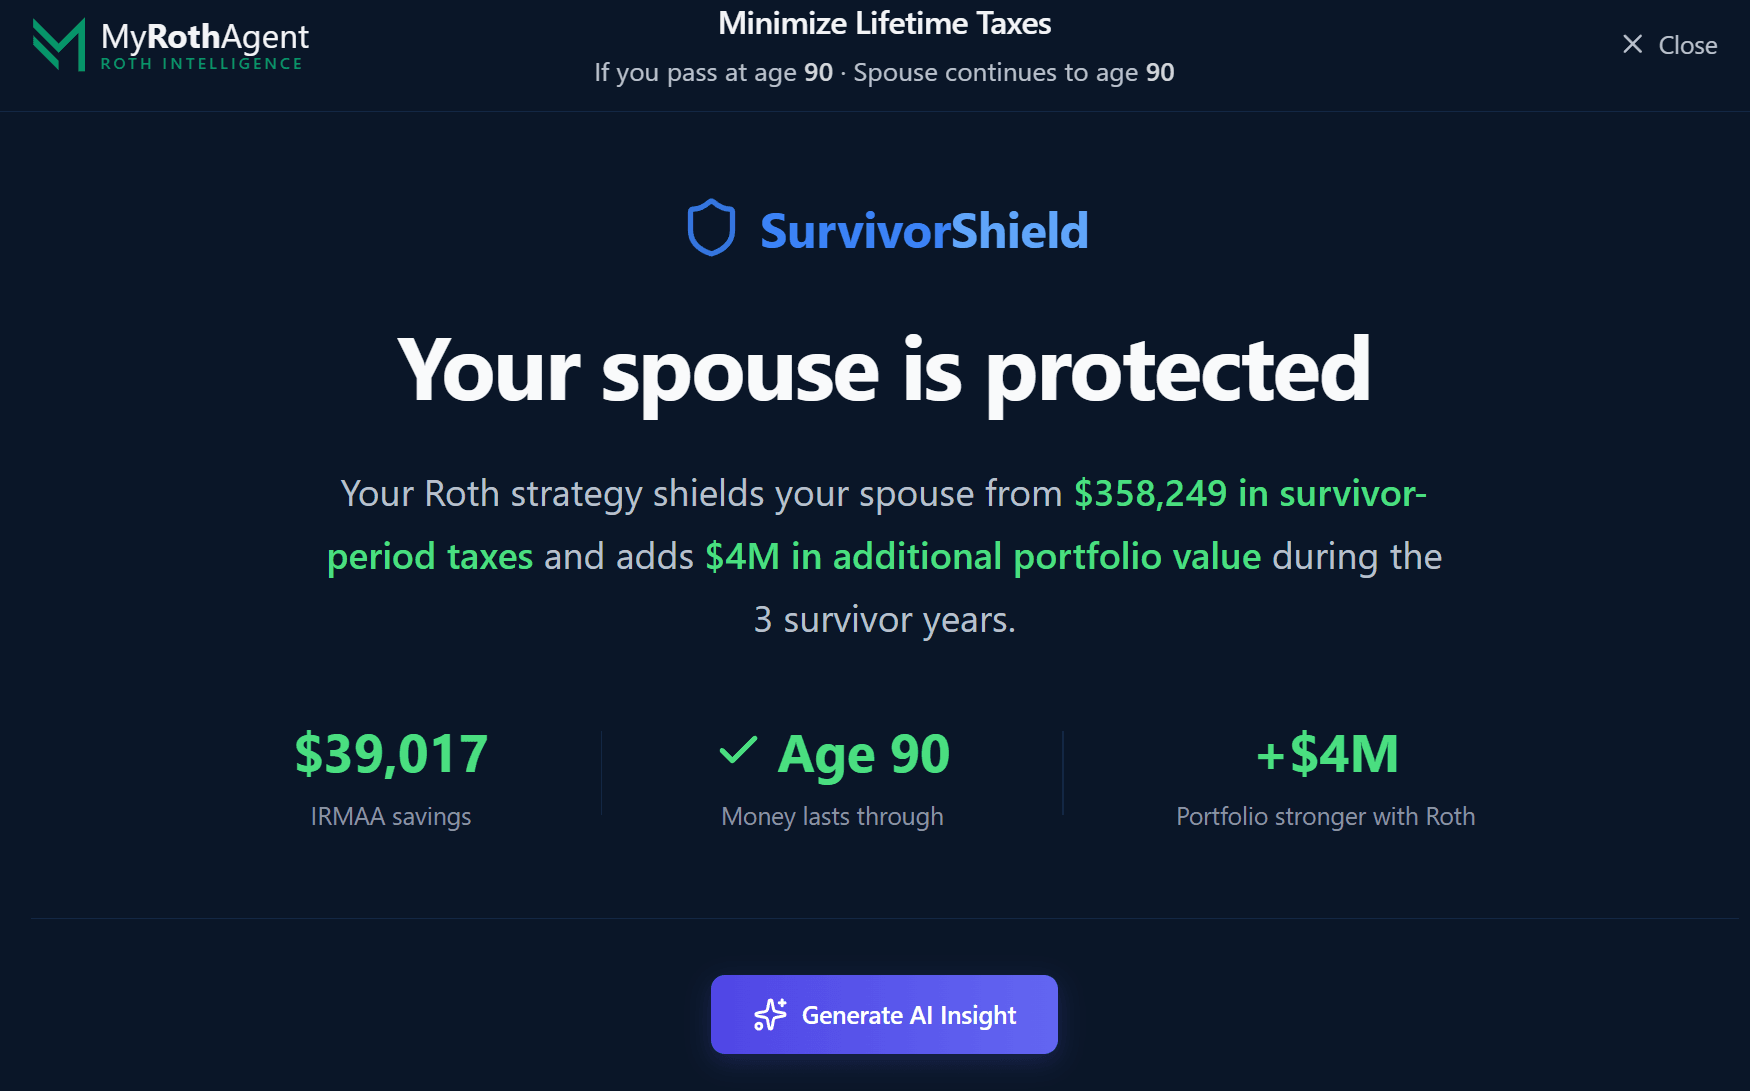
SurvivorShield — Your spouse is protected. $358,249 in survivor-period taxes shielded, $4M additional portfolio value, $39,017 IRMAA savings, Age 90 money lasts through.
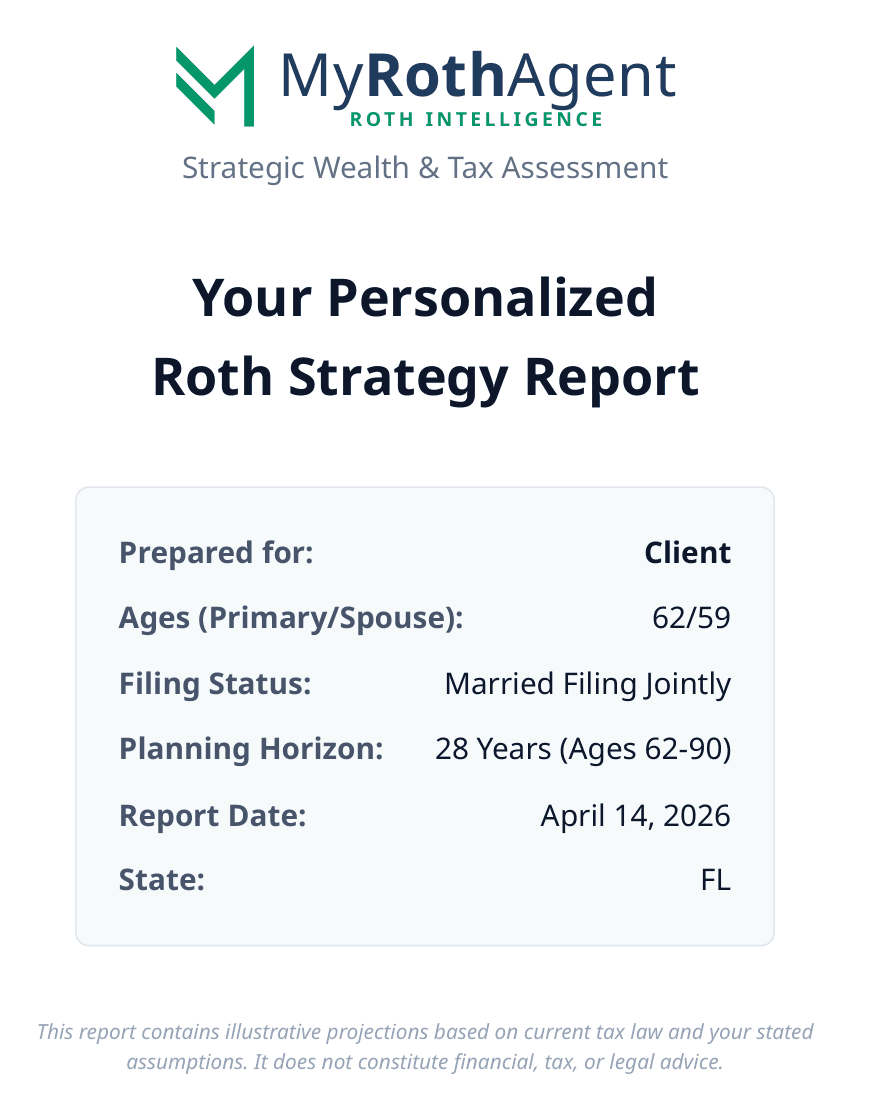
Your Personalized Roth Strategy Report — MyRothAgent Strategic Wealth and Tax Assessment. Prepared for Client, ages 62 and 59, Married Filing Jointly, 28-year planning horizon, FL.

See what your family stands to gain — in minutes, for free.

MyRothAgent compares every Roth conversion strategy against your baseline — year by year, bracket by bracket, IRMAA tier by IRMAA tier.

Free RMD analysis, no strings
No email, no credit card, no account linking. Enter your numbers and see the impact in minutes.
Built on IRS Pub 590-B
Plus 2026 federal tax tables, IRMAA thresholds, Joint Life Table, and SECURE Act 2.0 rules — all versioned.
104-column audit CSV included
Every calculation — RMDs, brackets, IRMAA tiers, balances — explained. Hand it to your CPA.
Made for DIY retirees, not advisors
Priced as a one-time $49 or $129/year — not as a percent of your portfolio.
Figures shown are from a sample MyRothAgent analysis (MFJ couple, ages 62 & 59, $3M pre-tax IRA). Your actual results will vary.
IRS Pub 590-B + SECURE Act 2.0
2026 federal tax tables
IRMAA-aware optimization
No account linking, ever
The Difference One Roth Strategy Makes

In one sample analysis: $940,449 less in lifetime taxes. $5.4 million more to heirs. Zero heir tax bill.

This is a sample MyRothAgent analysis: MFJ couple, ages 62 & 59, $3M in pre-tax IRAs, Florida — compared to what happens if they do nothing. Your actual results will vary.

Do Nothing (Baseline)
$7.0M to heirs
$8.4MLegacy Value
After-Tax to Heirs (83%)
Heir Taxes (17%)
$1.8M
Lifetime Tax
$1.4M
Heir Tax Bill
Minimize Lifetime Taxes (Preferred)
$12.4M to heirs
$12.4MLegacy Value
After-Tax to Heirs (100%)
Heir Taxes (0%)
$864K
Lifetime Tax
$0
Heir Tax Bill

Same couple. Same assumptions. $5.4 million more after-tax to heirs — just from choosing the right Roth conversion path.

How It Works

Free to start. Built to use every year.

From a 13-field RMD wake-up call to a CPA-ready Roth strategy you maintain through retirement.
1
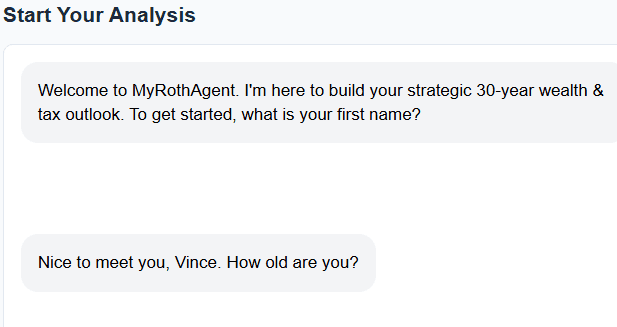
MyRothAgent free RMD wizard — chat-style interface asking for name, age, and pre-tax retirement account balance.
See what RMDs will cost you
Answer 13 questions in a chat-style wizard. Get your 30-year RMD projection — total taxes, IRMAA exposure, what the IRS extracts if you do nothing. Want the full report with deeper IRMAA detail and a downloadable PDF? Just add your email — still free.
Free · no email for the analysis
2
Scenario Optimizer comparing 5 strategies side-by-side
Build multiple Roth strategies
A 5-screen wizard captures your full picture. Build as many strategies as you want — each modeling 5 custom scenarios — with detailed tax analysis, AI Insights on every chart, and SurvivorShield protection for your spouse. Compare all 5 side-by-side instead of one at a time.
$49 one-time · $129/yr
3
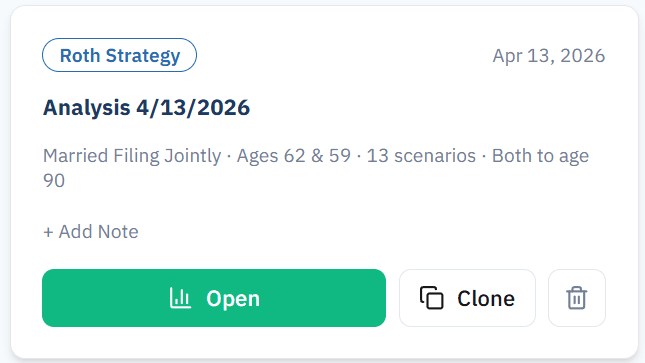
My Roth Dashboard showing multiple saved Roth strategies and downloadable strategy reports — re-runnable any time.
Re-run as life changes
Save your strategies. Come back through the year — replace estimates with actuals as tax filings finalize, react to law changes (TCJA expiration, OBBBA), and generate fresh CPA-ready reports for your advisor. Roth planning isn't one-and-done — it's a yearly ritual.
Unlimited re-runs included
AI Insights
Trained on IRS Pub 590-B, not internet opinions

The math is the math. AI tells you what it means.

Every Roth strategy, every chart, every surcharge comes with a plain-English explanation — grounded in your actual numbers. No hallucinated advice. No generic templates.
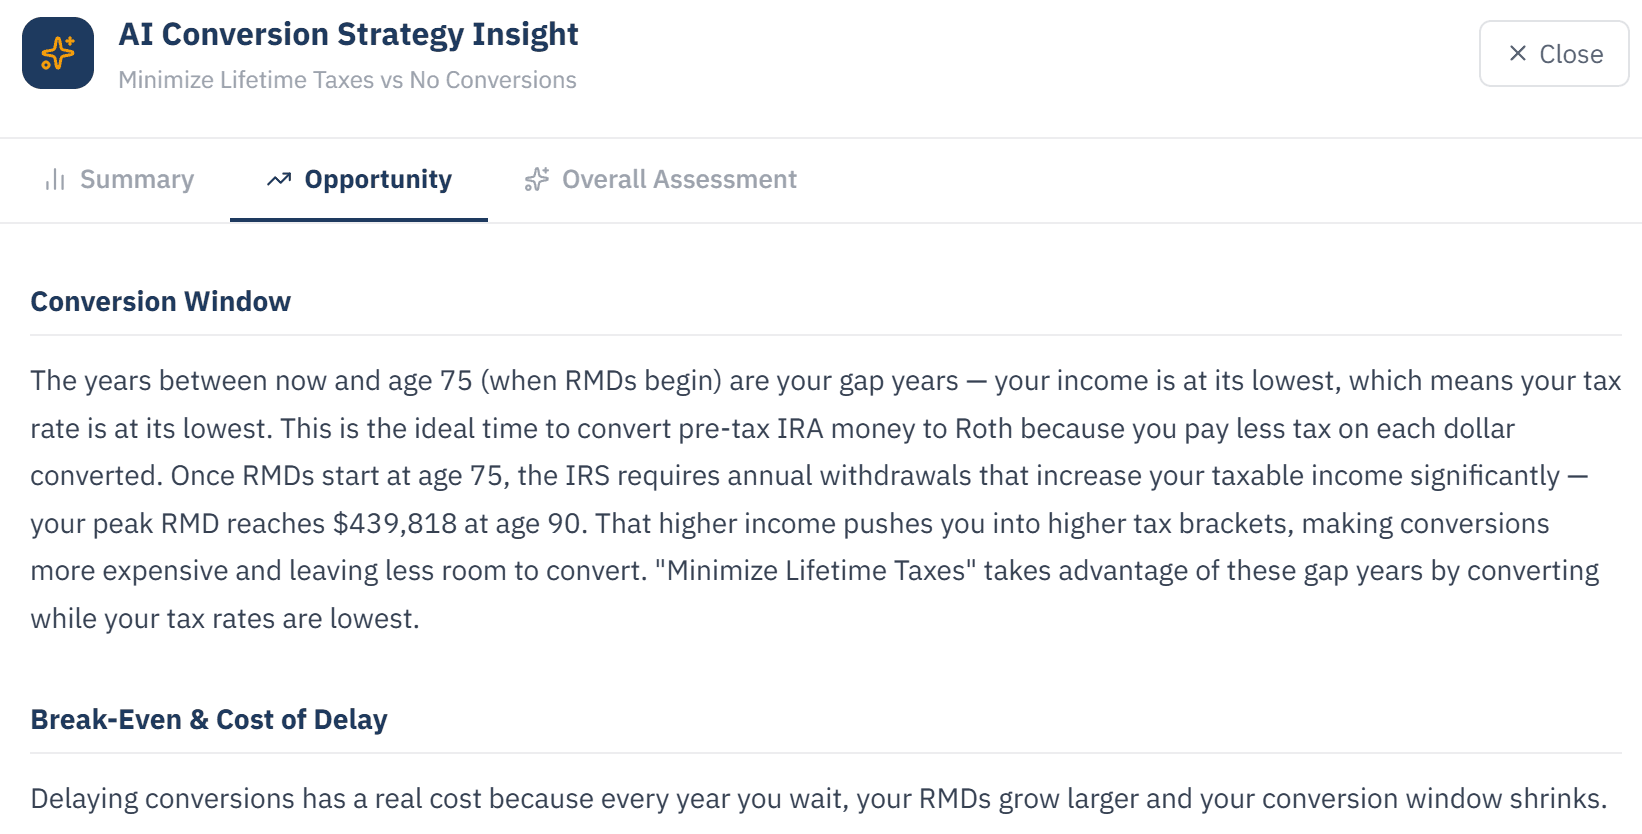
Under "Base Case (No Conversions)", lifetime taxes are $1,804,830. Under "Minimize Lifetime Taxes", they drop to $864,381 — a savings of $940,449. The strategy triggers Medicare IRMAA surcharges for 5 years, totaling $37,573, but this short-term cost is minimal compared to the lifetime tax savings.
AI Conversion Strategy Insight — Minimize Lifetime Taxes vs No Conversions. Opportunity tab showing Conversion Window paragraph explaining gap years between now and age 75 RMD start, with the Break-Even & Cost of Delay section beginning below.
Nothing is Hidden

Every number. Every year. Every assumption — downloadable.

Generalist retirement tools give you a chat interface. MyRothAgent gives you a 104-column Roth optimization audit CSV covering RMD divisors, bracket ceilings, IRMAA lookback MAGI and tier, Social Security provisional income, bracket headroom, growth calculations, and balance reconciliations — including per-spouse balance splits — every year, every row.

Hand it to your CPA
Every calculation line shows the input, the rule version, and the result. Audit-ready.
Verify the tax math yourself
Source tables for every bracket, standard deduction, and IRMAA tier are cited with version IDs.
No black-box AI
AI explains; the engine computes. You can re-derive every number by hand if you want to.
scenario_audit.csv104 columns · 31 years
YearAges P/SConversionProvisional Inc.BracketFed TaxIRMAA TierIRMAA $Roth Bal.
203168 / 65$202,245$296,97624.0%$50,493Tier 1$2,599$2.14M
203269 / 66$205,170$303,63324.0%$52,054Tier 4$14,737$2.48M
203370 / 67$211,732$310,56024.0%$53,128Tier 1$2,730$2.84M
203471 / 68$215,490$314,62524.0%$53,499Tier 1$2,798$3.22M
203572 / 69$223,450$323,09624.0%$54,913Tier 1$2,868$3.63M
203673 / 70$231,749$331,81324.0%$56,368Tier 1$2,940$4.08M
203774 / 71$176,628$277,11322.0%$42,898Tier 1$3,014$4.49M
204077 / 74$0$108,70912.0%$9,486Tier 1$3,245$5.54M
Exported with every paid analysis
Built For Serious Roth Optimization, Not Just Generic Planning

Nine things generalist retirement
planning tools can't do.

Designed for retirees who want to drill down, change one variable, and see the ripple — instantly.

5 Roth scenarios side-by-side
See every Roth strategy on one screen — Minimize Lifetime Tax, Maximize Legacy, Fill the 24% Bracket, Accelerated, Custom — with delta pills against your baseline. Most tools force you to compare one at a time.
Add Roth scenarios from templates
Spin up a custom Roth scenario in seconds — pick a template, tweak the parameters, see the impact instantly. No five-screen rebuild every time you want to test an idea.
Year-by-year tax math
Every year, every line: federal tax, IRMAA tier, RMD divisor, conversion amount, balance reconciliation. See exactly how each number was produced — not a black box.
Snapshot any age
Click to see balances, taxes, RMDs, and IRMAA at age 75, 80, or 90 — instantly. No scrolling through 30-year tables to find the year that matters to you.
BreakEven Radar
See exactly when your Roth conversion costs are recouped — the age a Scenario pulls ahead of No Conversions. No back-of-envelope math.
Horizon & longevity, in-line
Change your planning horizon and longevity assumption right from the comparison screen — no menu diving, no re-runs, no losing your place.
SurvivorShield
Models what happens when one spouse dies — the "widow penalty" of Single brackets on a smaller income base. Most tools ignore the survivor years entirely.
AI Insights on every section
Plain-English explanations grounded in your actual numbers. Why this Roth strategy beats the baseline, what triggers IRMAA in year 68, what happens to your spouse — all explained.
104-column audit CSV + PDF
Every calculation reproducible. Hand the PDF and CSV to your CPA or CFP — they can verify the math themselves. Your advisor's job gets easier, not replaced.
Pricing

Start free. Upgrade when you see the value.

Free RMD Analysis
$0
See what RMDs will cost you over 30 years — free, forever, no account required.
  • 30-year RMD projection
  • Effective tax rate curve
  • AI plain-English summary
Start Free Analysis
Annual
$129
per year
Rerun your Roth analysis every quarter — or whenever tax law, markets, or life changes.
  • Everything in Roth Strategy
  • Unlimited re-runs
  • Tax-law update alerts
Subscribe Annually
AI Insights: The Real Cost of Delay

Every year you wait costs real money — and your Roth conversion window keeps shrinking.

Delaying Roth conversions has a real cost: each year you wait, your RMDs grow larger and your conversion window narrows. MyRothAgent re-runs your plan as if you started 1 year and 5 years later and shows the difference. In this sample analysis (a married couple, ages 63 and 60, $3M pre-tax, plan "Max Legacy, Timed"), here's what delaying Roth conversions costs.

1 year
delay
+$11,384
More lifetime tax + IRMAA
−$124,451
Less Net Legacy Value
5 year
delay
+$246,651
More lifetime tax + IRMAA
−$656,223
Less Net Legacy Value
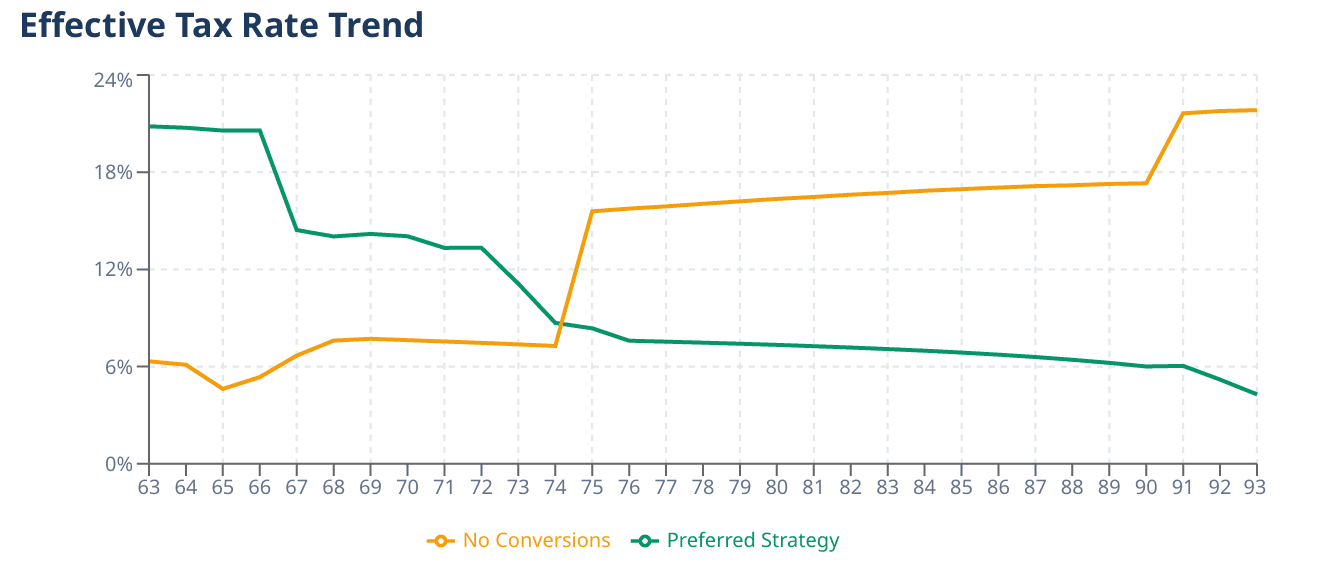
Effective Tax Rate — Baseline vs Strategy
"No Conversions" (orange) climbs as RMDs hit. The "Preferred Strategy" (green) drops as Roth dollars replace taxable distributions.
Effective tax rate chart — No Conversions (orange) climbs from 12% to ~28% as RMDs hit; Preferred Strategy (green) drops from ~24% at age 63 to ~6% after conversions complete; lines cross near age 83.
Illustration from a sample MFJ analysis, ages 62 & 59

See what your RMDs will cost you — free, in minutes.

Thirteen fields. No account linking. No credit card.

Start Free RMD Analysis
Built on IRS Pub 590-B2025 tax tablesNot affiliated with your advisor
Important Disclosures

MyRothAgent is an educational software tool. We are not a registered investment adviser, broker-dealer, CPA, tax preparer, or law firm, and nothing in MyRothAgent is investment, tax, or legal advice. All figures are hypothetical projections based on the information you provide and our stated assumptions, using IRS rules in effect for 2026, and are not guarantees of future results. Consult a qualified tax professional before acting on Roth conversions, RMDs, or your retirement plan.

No guarantee of results. All figures shown are modeled projections based on user-entered inputs and assumptions in effect at calculation time. Actual tax outcomes, investment growth, Social Security benefits, IRMAA surcharges, and account balances will differ. Past performance and projected returns are not guarantees of future results.

Tax law and rules change. Projections are based on current federal tax tables, IRMAA thresholds, RMD divisors (IRS Pub 590-B, Joint Life Table), and SECURE Act 2.0 provisions. Future changes to federal or state tax law, Social Security, Medicare, or retirement-account rules may materially affect results.

Sample data. All dollar figures shown on this page are from a hypothetical MyRothAgent analysis — Married Filing Jointly couple, ages 62 & 59, Florida resident, $3M pre-tax IRA, $500K taxable account — except the cost-of-delay figures, which come from a second hypothetical analysis (Married Filing Jointly, ages 63 & 60, $3M pre-tax IRA). All are illustrative only. Your actual results will vary based on your inputs, tax-law changes, and market performance.

Full Terms of Service and Privacy Policy. A complete Terms of Service and Privacy Policy — including details on data collection, AI processing, payment handling, and your CCPA/GDPR rights — govern your use of MyRothAgent and will be published before paid tiers become available. By using this site you agree to the disclosures above.

© 2026 MyRothAgent. Not affiliated with any financial advisor, custodian, or government agency.